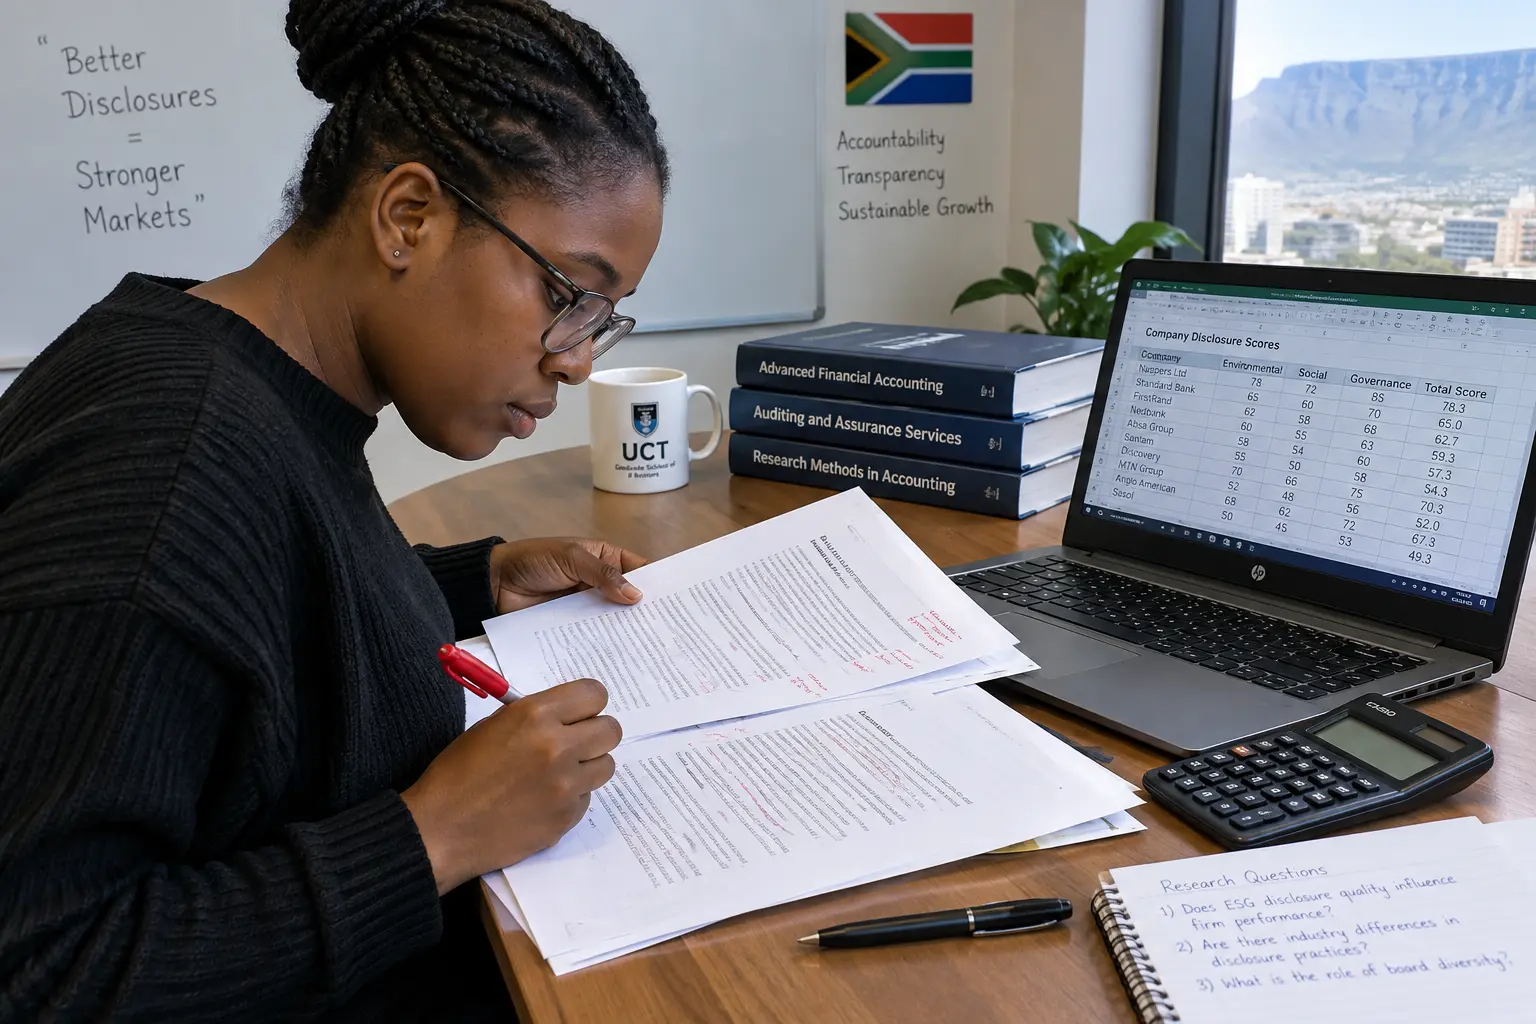
Three objections come up again and again when South African accounting research reports are sent back: citing a superseded governance code or accounting standard as if it were still current, building a data-collection method that cannot actually be repeated from the description given, and mismatching the statistical or content-analysis method to the research question. Each has a specific, checkable fix, and each is preventable with a targeted re-check before submission rather than a full rewrite.
Why is an outdated code or standard such a frequent objection?
South African corporate governance and financial-reporting rules change on a cycle most students do not track closely enough. The clearest recent example: the King IV Report on Corporate Governance for South Africa (2016) has been succeeded by the King V Code on Corporate Governance for South Africa, published by the Institute of Directors in Southern Africa (IoDSA) on 31 October 2025 and effective for financial years beginning on or after 1 January 2026. A research report citing King IV as the current operative code, without noting the transition, is citing governance guidance that no longer applies to the latest reporting years. The fix is procedural: before your final proofread, re-check every named standard, code and Act against its current status, and where your sample spans the transition period, state clearly which code applied to which reporting year in your sample rather than treating the whole period as governed by one code.
What does a data-collection method examiners cannot verify look like?
A disclosure-index or content-analysis study that does not state, in advance, where in the report to look, what counts as a “yes,” and what to do when the answer is ambiguous, produces scores a second coder (or an examiner) cannot reproduce from the description alone. A vague instruction such as “scored for ESG disclosure” tells an examiner nothing about how a borderline case was handled. The fix: write the scoring protocol as a three-part rule before you score a single company — the specific report section to check, the exact wording or detail that counts as present, and how a partial or ambiguous disclosure is scored — and keep a note of every item you had to judge, so a supervisor spot-checking your scores can follow your reasoning rather than simply trust it.
How does citation currency factor into a rejection?
Beyond the King IV/King V transition, accounting research reports commonly cite an IFRS standard, a SAICA guidance note or a JSE listing requirement without checking whether it has since been amended or withdrawn. IFRS standards are periodically revised, and a research report analysing disclosure against a specific standard’s requirements needs to name the exact standard and its effective version for the reporting period studied, not assume the version taught in a lecture two years ago is still current. Check the current standard directly from IFRS Foundation or SAICA’s own technical resources before naming a specific requirement in your methodology or findings.
What methodology mismatches trip up accounting research reports specifically?
A frequent mismatch is choosing a statistical test that does not fit the data structure — running a correlation or regression on a sample too small for the test to have meaningful power, or testing a disclosure-index score (which is often not normally distributed) with a test that assumes normality without checking. The general test-selection logic the site’s guide to choosing an analysis method for a South African accounting research report works through applies directly here; the accounting-specific addition is checking your disclosure-index or financial-ratio data’s distribution before committing to a parametric test, and reporting the check explicitly rather than assuming normality.
What does a weak claim look like next to a properly defended one?
Weak, unscoped: “JSE-listed companies have improved their ESG disclosure under King IV.” This asserts a trend without naming a specific sample, time period, disclosure measure, or the fact that King IV has since been succeeded. Properly defended: “Among a purposively selected sample of 18 JSE-listed retail companies, the mean disclosure-index score (built against a checklist adapted from the King IV disclosure principles, applying King IV for reporting years 2020–2024 and noting the transition to King V for financial years from 2026) increased from 0.61 to 0.78 over the study period, though the small sample size limits generalisability beyond the retail sector.” The second version names the sample, states the exact governance-code period covered, reports a specific measured figure with its checklist source, and states the limitation the small sample creates — everything an examiner needs to evaluate the claim on its own terms. The specific figures here are illustrative and fictional, built to show the shape of a defensible claim, not a real finding.
How do IFRS and King-code citation errors differ from each other?
An IFRS citation error is usually a currency problem — citing a superseded version of a specific standard. A King-code citation error is more often a scope problem — treating the code as a set of binding rules rather than the apply-and-explain framework it actually is, where a company states how it applies each principle or explains why it does not, rather than complying with a fixed checklist. A research report that scores King-code disclosure as a simple binary compliance checklist, without accounting for the apply-and-explain structure, is applying the wrong logic to the source material; state explicitly in your methodology that you are scoring the presence and quality of a company’s own apply-or-explain statement, not compliance with a mandatory rule.
What does a properly written scoring protocol look like, end to end?
Take one illustrative King-code item: “the company discloses whether an external assurance provider reviewed its sustainability report.” A defensible scoring protocol states, in advance, three things. First, where to look — typically the sustainability or ESG section and the assurance statement near the auditor’s report, not the whole document searched at random. Second, what counts as present — a named external assurance provider and a stated scope of assurance (limited or reasonable), not a general sentence such as “we are committed to transparent reporting.” Third, what to do when the answer is ambiguous — for example, a report that names an assurance provider but does not state the scope is scored as a partial disclosure, provided your protocol defines that partial category in advance rather than inventing one mid-sample. Writing this three-part protocol down before scoring the first company, and keeping a short note explaining any item you had to judge, is what lets a second coder or your supervisor reproduce your decision rather than simply trust it.
What if my supervisor’s objection changes between drafts?
Before assuming a new and unrelated objection has appeared, check whether an earlier round of written feedback was only partly addressed — a comment about citation currency in one section often applies equally to a similar citation elsewhere in the report that was not corrected in the same pass. Where a genuinely new point does emerge late, it is worth checking directly whether a governance code, standard or regulation changed between your drafts, given how frequently this specific area of South African accounting practice is revised.
How does this differ from the site’s existing accounting content?
The site’s guides to 40 accounting and CA(SA) research report topics and data sources for an accounting dissertation cover topic selection and where the underlying data comes from. This piece is a different job — the specific objections examiners raise once a topic is chosen, data is collected and a draft exists, and the fix for each.
Fixing citation currency and methodology gaps before resubmission
Re-checking every cited standard and code against its current status, rebuilding a scoring protocol into three explicit parts, and matching your statistical test to your actual data structure is exactly the kind of source-by-source revision work Tesify handles well, while every judgement about your data and your argument stays yours and the report stays 100% written by you. More than 9,000 students have used Tesify, across 15,000+ chapters. Revise your accounting research report with Tesify before you resubmit.
Frequently asked questions
Is King IV still acceptable to cite for a study covering reporting years before 2026?
Yes, provided you cite it as the code that applied to that specific reporting period and note explicitly that King V succeeded it for financial years from 1 January 2026, rather than presenting King IV as the current code without qualification.
How do I check whether an IFRS standard I am relying on has been amended?
Check the standard’s current version directly through the IFRS Foundation’s own published standards or your university library’s accounting standards database, rather than relying on a textbook or lecture note that may predate a revision.
Is a small sample size always an examiner objection on its own?
Not on its own — a small, purposively selected sample is a legitimate design where justified and its limitations stated explicitly; the objection arises when a small sample is presented as if it supported a broader generalisation than it can.
What if two companies in my sample interpret an apply-and-explain principle differently?
That variation is itself part of what a King-code disclosure study is measuring; report it explicitly rather than forcing both companies into the same binary score, and use it as an analytical point in your discussion rather than treating it as a scoring problem to eliminate.
Do I need to re-check every citation, or only the ones flagged by my supervisor?
Check every citation to a standard, code or regulation, not only the flagged ones — an examiner who finds one uncorrected currency error is more likely to check the rest of your citations closely, so a full pass protects the whole report’s credibility.
Can I use a commercial ESG rating instead of building my own disclosure index?
Yes, but name the specific provider, the exact score date and methodology version used, and acknowledge that different rating providers do not always agree with each other, a known limitation in this literature.
How many objections is normal before an accounting research report is accepted?
There is no fixed number; it depends on the faculty, the degree level and how far the first submission was from the expected standard. Treat each round of feedback as a full checklist to clear, not a partial one.
Does the King IV to King V transition affect a report already submitted before 31 October 2025?
A report submitted and examined before that date correctly treated King IV as current; the issue arises only where a report is being revised, resubmitted, or newly written after the transition date without updating the governance-code reference to reflect it.
Should I mention my scoring protocol’s ambiguous-case rule in the main text or only in an appendix?
State the rule itself in your methodology chapter’s main text, since it is a core part of how your data was produced; a full worked log of every ambiguous case you judged can sit in an appendix, referenced from the main text rather than repeated in full there.